By Lillah Grey September 24, 2026
Kentucky imposes a 6% statewide sales tax and has no ordinary local sales and use taxes. Separately, cities authorized by KRS 91A.400 may enact a restaurant license tax of up to 3%. Authorization does not prove a levy exists. Verify the city’s current ordinance and rate; if the local tax is passed to customers, Kentucky’s sales-tax stacking rule applies.
Rates, statutes, regulations, and local filing details in this guide were researched through September 24, 2026.
Restaurant Owner Quick Check
- Is my city on the KRS 91A.400 authorized-city registry?
- Has the city actually enacted a restaurant tax?
- What is the current locally enacted rate?
- Which sales and charges enter the local tax base?
- Does my POS calculate Kentucky sales tax using the correct base after the local-tax treatment?
- Where and when do I file the state and local returns?
Kentucky Restaurant Tax: The Core Rule
The Kentucky restaurant tax question has three layers that should stay separate in the POS and accounting system.
- Layer 1 — Kentucky sales tax: Kentucky imposes sales tax at 6% of gross receipts subject to tax. The Kentucky Department of Revenue explicitly states that there are no local sales and use taxes in Kentucky.
- Layer 2 — no ordinary city sales tax: A restaurant should therefore not treat a city restaurant levy as though Kentucky had simply authorized Louisville-style, county-style, or municipal add-on sales-tax rates.
- Layer 3 — a separate restaurant levy: KRS 91A.400 allows an “authorized city” to enact a restaurant tax of up to 3% of retail sales by restaurants doing business in that city. For Kentucky sales-tax purposes, 103 KAR 27:220 classifies that levy as a license tax.
That is how both statements can be true: Kentucky has no general local sales tax, while certain cities can impose a separate Kentucky restaurant license tax.
Which Kentucky Cities Are Authorized to Charge a Restaurant Tax?
The controlling statute, KRS 91A.400, defines an “authorized city” by reference to the registry maintained by the Kentucky Department for Local Government. It also permits the legislative body of an authorized city to impose a restaurant tax of no more than 3% of retail restaurant sales within the city.
That historical classification date matters. Kentucky should not be described as still operating its former numbered city-class system generally; KRS 91A.400 preserves that historical classification snapshot specifically to determine eligibility.
DLG’s current municipal site continues to publish the KRS 91A.400 City Registry for Restaurant Tax alongside its historical city-class files.
A 2026 proposal, HB 808, would have expanded restaurant-tax authority to all home-rule-class cities and removed the DLG-registry restriction. As of September 24, 2026, its last legislative action remained a March 13 return to the House Local Government Committee; it did not replace the current statute.
Authorized Does Not Mean the Tax Is Actually Being Charged
The DLG registry answers only the first question: Can this city legally use KRS 91A.400?
The second question requires local research: Did the city council actually enact a restaurant-tax ordinance, what rate is currently effective, and how is it administered?
This review verified active restaurant levies from current primary local sources in 15 jurisdictions, including Bardstown, Berea, Cave City, Elizabethtown, Fulton, Grayson, Horse Cave, Leitchfield, Madisonville, Morehead, Mount Vernon, Munfordville, Pikeville, Shelbyville, and Simpsonville. The detailed city-by-city verification table follows the article.
Being on the KRS 91A.400 registry shows statutory authorization. It does not, by itself, prove that the city currently levies the tax.
Local Restaurant Tax Kentucky Cities: Verified Rates and Filing Authorities
Rates and local filing details verified September 24, 2026. This table covers jurisdictions whose current restaurant-tax rules could be verified from available primary sources; it is not presented as an exhaustive list of every active Kentucky restaurant levy. Restaurants should confirm their own city before relying on the list.
| City | Current Restaurant Tax? | Rate | Effective/Verified As Of | Remit To | Filing Frequency / Due Date | Primary Source |
| Bardstown | Yes | 1% | Current 2026 code; verified 9/24/26 | City CFO; city transfers collections to Bardstown-Nelson County Tourist & Convention Commission | Monthly; 20th | Current city code §§119.02, 119.03, 119.06 |
| Berea | Yes | 3% | Verified 9/24/26 | City of Berea Finance | Quarterly; last day of month following quarter | Current city Finance restaurant-tax page |
| Cave City | Yes | 3% | Effective 7/1/2015; verified 9/24/26 | City / Clerk-Treasurer under current return process | Monthly; 20 days after month | City code §118.02 and city return materials |
| Elizabethtown | Yes | 2% | Verified 9/24/26 | City Director of Finance; funds transferred to tourism bureau | Monthly; received by 20th | City ordinance and current tax page |
| Fulton | Yes | 2% | Effective 7/1/2026 | City Clerk | Monthly; current reporting section says by 30th day after month | Ordinance 2026-10/current §44-362 |
| Grayson | Yes | 3% | Verified 9/24/26 | City Clerk; proceeds to Tourist & Convention Commission | Monthly; 15th | City code §69.003 |
| Horse Cave | Yes | 3% | Verified 9/24/26 | City of Horse Cave under city restaurant-tax form | Monthly; 20th | Current city Forms & Ordinances page |
| Leitchfield | Yes | 3% | Effective 7/1/2011; current 2026 code | City Treasurer; funds to Tourism & Convention Commission | Monthly; 30 days after month-end | Current code §40.09 |
| Madisonville | Yes | 3% | Current 2026 code | City Director of Finance; funds disbursed to commission | Monthly; 20th | §§123.02–123.04 |
| Morehead | Yes | 3% | Current 2026 code | City Clerk/city treasury; funds disbursed to Morehead-Rowan County commission | Monthly; 20th | §§34.47–34.48 |
| Mount Vernon | Yes | 3% | Effective 1/2/2008; current guidance verified 9/24/26 | Mt. Vernon-Rockcastle County Tourism Commission | Monthly; received by 20th | Official tourism commission tax guidance |
| Munfordville | Yes | 3% | Current published code | City Clerk; city transfers proceeds to Tourism & Convention Commission | Monthly; 20th | City code §37.07 |
| Pikeville | Yes | 3% | Effective 2/1/2017; current 2026 code | City Division of Tax Collection / Occupational Tax Administrator | Monthly; 20th; zero return required | Current §35.46 and official return |
| Shelbyville | Yes | 3% | Effective 1/1/2016; current code verified 9/24/26 | Tourism Commission | Monthly; 30 days after month-end | City code §69.002 |
| Simpsonville | Yes | 3% | Effective 4/1/2014; current published code | Tourism Commission | Monthly; 30 days after month-end | City code §116.02 |
Fulton caution: Ordinance 2026-10 clearly raised the rate from 1% to 2% for taxable sales beginning July 1, 2026 and instructed city staff to update the monthly return. The separately published §44-363 reporting provision still contains the former 1% computation language. Businesses should obtain the updated city form or written City Clerk confirmation rather than using that stale computation sentence.
How High Can the 3 Percent Restaurant Tax Be?
The phrase 3 percent restaurant tax describes the statutory ceiling, not a statewide rate. KRS 91A.400 allows a rate not exceeding 3%.
Actual rates differ. Current primary sources reviewed here show Bardstown at 1%, Elizabethtown and Fulton at 2%, and numerous other verified cities at 3%.
A POS administrator therefore needs the enacted city rate, not merely the statutory maximum.
Who Keeps the Restaurant-Tax Money?
KRS 91A.400 requires money collected under the statute to be turned over to the tourist and convention commission established for the city under KRS Chapter 91A.
That does not mean merchants everywhere send returns directly to a tourism commission. Administration varies. Mount Vernon requires monthly payment directly to the Mt.
Vernon-Rockcastle County Tourism Commission; Elizabethtown collects through its City Director of Finance before transferring the net collections to its tourism organization; Munfordville collects through the City Clerk and then transfers the funds.
The Kentucky Department of Revenue receives the restaurant’s state sales tax, not these local KRS 91A.400 returns.
Tourism Commission Restaurant Tax vs Kentucky’s 6% Sales Tax
A tourism commission restaurant tax and Kentucky sales tax may appear on the same receipt, but they are different obligations.
| Feature | Kentucky State Sales Tax | Local Restaurant Tax |
| Legal authority | KRS Chapter 139 | KRS 91A.400 plus local ordinance |
| Rate | 6% | Up to 3%; actual city rate varies |
| Geographic scope | Statewide | Only an authorized city that enacts it |
| Administrator | Kentucky Department of Revenue | City, finance office, or tourism commission depending on ordinance |
| Tax base | Kentucky taxable gross receipts | Local restaurant-sales base defined by ordinance |
| Filing | MyTaxes/DOR | Separate local return or portal |
| Frequency | DOR-assigned | City-specific |
| POS treatment | State tax code | Separate local code with correct stacking |
Kentucky’s state prepared-food rules and a city’s restaurant-tax ordinance should therefore be mapped separately rather than assumed to have identical bases.
Does the 3% Restaurant Tax Get Charged Before or After the 6% State Tax?
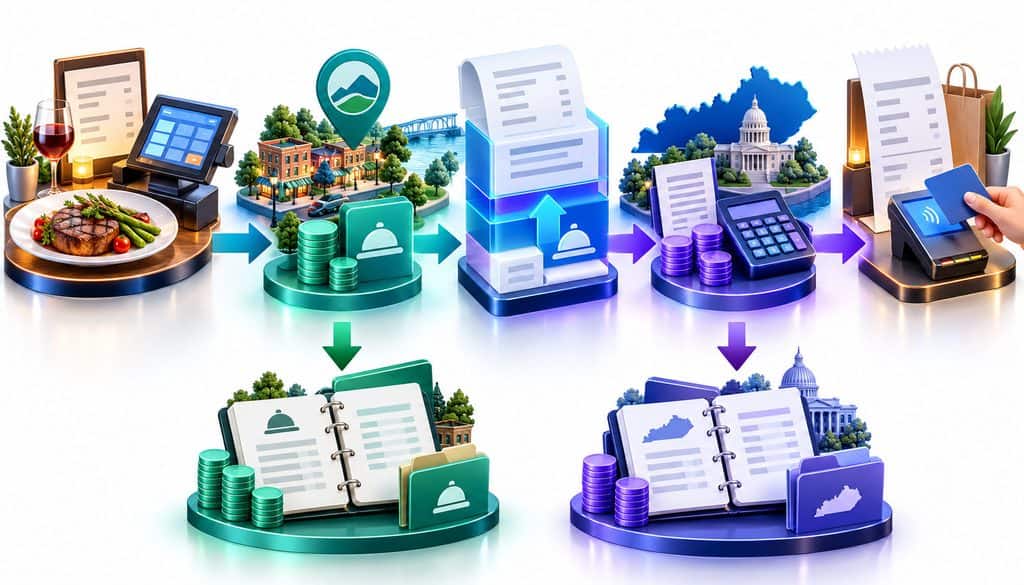
The controlling Kentucky restaurant-transactions regulation, 103 KAR 27:220, classifies a city restaurant tax imposed under KRS 91A.400 as a license tax. When the restaurant passes that charge on to the customer, the regulation says the amount becomes part of gross receipts subject to Kentucky sales tax under KRS 139.010.
Practically, the local levy is calculated first on the locally defined restaurant-tax base. The passed-through local tax is then part of the amount on which the 6% Kentucky sales tax is calculated.
Illustrative example using Mount Vernon, a verified 3% restaurant-tax jurisdiction:
| Calculation | Amount |
| Menu/food subtotal | $100.00 |
| 3% local restaurant tax | $3.00 |
| Kentucky sales-tax base | $103.00 |
| 6% Kentucky sales tax | $6.18 |
| Customer total | $109.18 |
Mount Vernon’s official tourism guidance uses this same sequence: local restaurant tax first, then Kentucky sales tax on the increased amount.
Some ordinances, including Pikeville’s, allow the restaurant to absorb rather than pass through its local tax. In that situation, do not manufacture a customer-facing local charge; configure the transaction around the ordinance and the actual manner in which the restaurant bears or passes through the liability.
Why “3% + 6% = 9%” Can Be Misleading
Simply adding nominal rates assumes each tax is calculated independently on the original $100.
In the example above, the customer pays $3 in local tax and $6.18 in state tax—a $9.18 addition—because Kentucky taxes the passed-through local license tax. Calling that configuration a flat 9% rate would lose the required calculation order.
Kentucky Restaurant POS Tax Setup
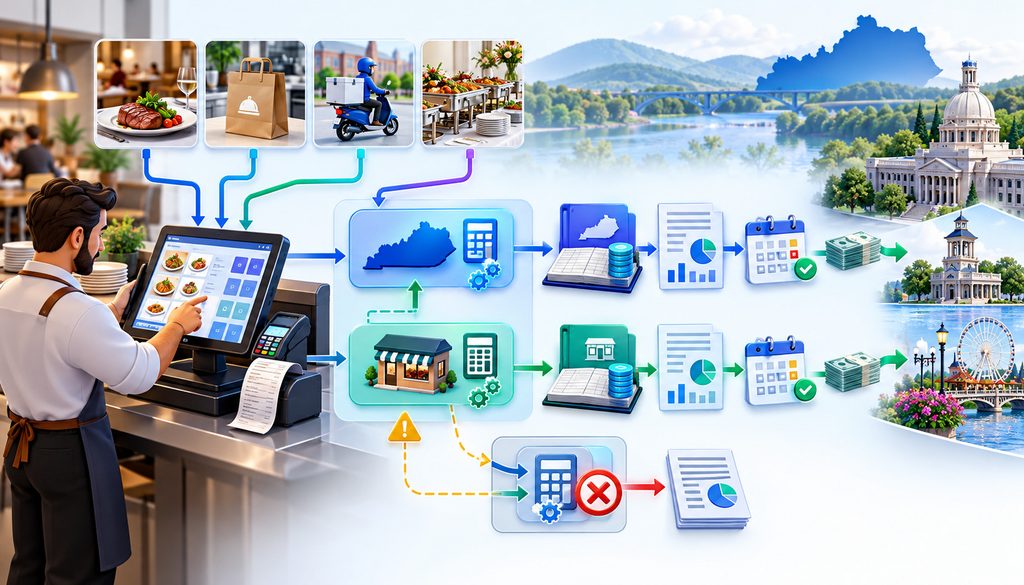
A reliable Kentucky restaurant POS tax setup keeps state and local obligations separate.
- Create Tax Code A — Kentucky State Sales Tax at 6%.
- Create Tax Code B — Local Restaurant License Tax at the verified city rate.
- Assign the city’s ordinance-defined base to Code B.
- Configure Code B to calculate before Code A when the local levy is passed through.
- Make the passed-through local tax enter Code A’s taxable base.
- Map dine-in, takeout, catering, delivery, alcohol, packaged items, and other categories individually where their treatment differs.
- Keep state and local amounts in separate reporting buckets.
- Map each tax to its own liability account.
- Test receipt rounding and tax calculations before deployment.
- Reconcile each liability report to its respective return.
Before activating the tax codes, make sure the POS can keep the state sales tax and local restaurant license tax in separate reporting buckets. An integrated point-of-sale system can make it easier to preserve transaction-level sales records while keeping checkout, reporting, and reconciliation connected.
Do not create one generic “9% tax” button unless a documented configuration produces exactly the tax bases and reporting required by both governments.
What the Customer Receipt Should Show
An operationally useful receipt can separately display:
Food subtotal …………… $100.00
Local restaurant tax ……… $3.00
Kentucky sales tax ……….. $6.18
Total ……………….. $109.18
Kentucky guidance requires state sales tax to be separately stated on a detailed receipt. Separate local tracking also makes POS reports, liability reconciliations, state returns, and local restaurant-tax returns easier to trace.
Do not treat the exact wording above as a universal local receipt mandate; check the applicable city ordinance.
Filing the State Tax and Local Restaurant Tax
Restaurants register Kentucky tax accounts through MyTaxes, which has handled sales and use tax since March 2025. Current DOR rules require online filing and payment for monthly, quarterly, and annual filer-frequency accounts unless a statutory waiver applies.
The regular state schedule uses the 20th following the reporting period for monthly, quarterly, and annual filings; accelerated monthly accounts generally use the 25th. A Kentucky sales-tax return remains required even when no sales or tax are due.
Local calendars are separate:
| Obligation | Administrator | Frequency | Due Date | Important Note |
| Kentucky sales tax | Kentucky DOR | Assigned monthly, quarterly, annual, or accelerated | Generally 20th; accelerated monthly generally 25th | File through MyTaxes |
| Berea restaurant tax | City of Berea Finance | Quarterly | Last day of month after quarter | Separate city return |
| Mount Vernon restaurant tax | Tourism Commission | Monthly | Received by 20th | Direct commission filing |
| Pikeville restaurant tax | City Division of Tax Collection | Monthly | 20th | Zero return required |
| Shelbyville restaurant tax | Tourism Commission | Monthly | 30 days after month-end | Direct local filing |
| Simpsonville restaurant tax | Tourism Commission | Monthly | 30 days after month-end | Direct local filing |
During month-end reconciliation, matching processor reports to gross card activity and bank deposits can help the accounting team separate sales, collected taxes, refunds, chargebacks, and processing fees before those amounts are posted to the wrong revenue or liability accounts.
How to Confirm Whether Your City Charges the Tax
Use this workflow before activating a local tax code:
- Identify the exact incorporated city where the restaurant operates.
- Check DLG’s KRS 91A.400 registry for statutory authorization.
- Search the current city code and recent ordinances.
- Check the official city finance or tax page.
- Check the official tourism or convention commission.
- Locate the current restaurant-tax return or instructions.
- Confirm the current rate and effective date.
- Confirm which sales and charges enter the local base.
- Confirm filing frequency and due date.
- Confirm the actual recipient of the return and payment.
- Save the source, ordinance number, and verification date with the POS configuration record.
If official sources conflict or omit a transaction type, obtain written confirmation from the city or commission administering that levy before changing the POS.
Delivery Orders
Kentucky state sales-tax gross receipts can include retailer delivery charges. KRS 139.010 expressly includes retailer delivery charges in gross receipts.
The local restaurant license tax is different. KRS 91A.400 does not supply one universal delivery-destination sourcing rule for every city ordinance. Mount Vernon, for example, expressly tells caterers, food trucks, and vendors serving or delivering food within the city to collect its restaurant tax; that local instruction should not be extrapolated to every Kentucky city.
To-Go and Takeout Orders
Takeout is not automatically outside a Kentucky local restaurant-tax base.
Leitchfield’s definition includes food prepared for consumption “on the premises or elsewhere,” while Mount Vernon’s definition similarly reaches qualifying off-premises prepared-food sales.
For Kentucky sales tax, separately analyze whether the item is taxable prepared food under KRS 139.485.
Catering
Catering requires jurisdiction-specific research rather than copying the dine-in tax setup.
Leitchfield expressly includes catering kitchens in its restaurant definition, and Mount Vernon includes catering and provides local guidance for food served or delivered within city limits. A caterer working across municipal boundaries should document the seller location, preparation location, event location, delivery location, and exact local ordinance before assigning the tax.
Third-Party Delivery Platforms
Kentucky’s marketplace-provider rules can shift state sales-tax collection and remittance to a qualifying marketplace provider for facilitated taxable sales. The current KRS 139.450, effective August 1, 2026, requires covered marketplace providers to collect Kentucky tax on facilitated taxable sales; KRS 139.550 addresses marketplace filing and remittance.
That does not automatically answer the city’s restaurant-license-tax question. Restaurants should confirm whether the local ordinance or administrator expects marketplace transactions in local gross sales and which party must remit them.
Taxable Prepared Food vs the Local Restaurant-Tax Base
KRS 139.485 generally exempts “food and food ingredients” but excludes prepared food, soft drinks, candy, alcohol, and several other categories from that definition. Prepared food includes, among other things, food sold heated, certain retailer-combined foods, and food sold with utensils, subject to statutory exceptions such as qualifying bakery items.
A local base can be different. Madisonville taxes food and nonalcoholic beverages; Pikeville’s return deducts non-food and alcoholic-beverage sales; Cave City uses “all food and beverages” language.
That is why prepared food sales tax Kentucky rules should not be copied wholesale into a local tax code.
Mandatory Gratuities, Service Charges, and Fees
For Kentucky state sales tax, 103 KAR 27:220 provides that charges added by a restaurant to prepared food—including mandatory gratuities, service charges, surcharges, and fees—are part of the selling price. A voluntary gratuity left by the customer is not subject to that tax.
The regulation does not establish that every city’s restaurant-tax ordinance uses precisely the same base. If a local ordinance is silent on mandatory gratuities, delivery fees, or service charges, confirm the local treatment instead of assuming the state result controls.
Four Illustrative Operating Examples
- Example 1 — verified 3% city: A Mount Vernon restaurant sells $100 of locally taxable food. It records $3 local tax, includes that passed-through tax in the state base, calculates $6.18 Kentucky sales tax, and separately remits state and tourism-commission liabilities.
- Example 2 — authorized city, levy not confirmed: A restaurant finds its city on the DLG registry but cannot locate a current ordinance, return, or finance instruction establishing an active levy. It should not activate a 3% tax simply because the city is authorized.
- Example 3 — caterer crossing city lines: A caterer based in one municipality serves an event in another. The operator checks both jurisdictions’ ordinances and local sourcing guidance rather than treating the permanent kitchen’s dine-in configuration as a statewide catering rule.
- Example 4 — one combined POS button: A restaurant records one combined charge instead of separate liabilities. Even if the customer total happens to look close, the controller can struggle to prove the Kentucky taxable base, reconcile the local return, or explain which money belongs to which government.
[Expert Quote Opportunity: Ask a Kentucky CPA or SALT professional to explain why restaurants should maintain separate POS liability accounts for Kentucky sales tax and a local restaurant tax.]
[Local Expert Quote Opportunity: Ask an official from a tourism/convention commission how restaurants should verify filing frequency after opening or changing ownership.]
Common Kentucky Restaurant Tax Mistakes
| Mistake | Why It Happens | Potential Result | Better Control |
| Assuming every city charges 3% | Confusing maximum with actual rate | Overcollection | Verify ordinance |
| Treating DLG registry as an active-tax list | Authorization confused with enactment | Unlawful/incorrect collection | Find current local ordinance/form |
| Calling it a local sales tax | Familiar terminology | Wrong legal/accounting treatment | Track as separate restaurant/license tax |
| Using one 9% POS rate | Nominal rates simply added | Wrong state taxable base | Separate tax codes |
| Sending both taxes to DOR | One receipt shows both | Local delinquency | Separate administrators |
| Copying another city’s calendar | Nearby cities look similar | Late local return | Maintain jurisdiction calendar |
| Ignoring takeout/delivery | Dine-in logic reused | Under/overcollection | Map transaction types |
| Assuming local and state bases match | Both involve food | Wrong taxability | Maintain separate tax matrices |
| Keeping an old city rate | POS configuration goes stale | Ongoing errors | Annual ordinance review |
| Failing to save source documents | Configuration lacks support | Audit/reconciliation difficulty | Date-stamped tax file |
FAQs
Does every Kentucky city charge a restaurant tax?
No. KRS 91A.400 limits authority to cities on the DLG registry, and an authorized city still must enact a local ordinance before a levy exists.
Is Kentucky’s restaurant tax a local sales tax?
Not in the sense of a general local sales and use tax. Kentucky DOR says Kentucky has no local sales and use taxes, while 103 KAR 27:220 classifies a KRS 91A.400 city restaurant tax as a license tax.
Which Kentucky cities are allowed to charge a 3 percent restaurant tax?
Cities appearing on the DLG KRS 91A.400 registry are the current statutorily authorized cities. The registry reflects cities that were fourth- or fifth-class cities on January 1, 2014.
Does being on the DLG registry mean the city currently charges the tax?
No. The registry proves authorization, not enactment. Check the current local ordinance, finance page, tax form, or tourism-commission instructions.
Is the local restaurant tax added before Kentucky’s 6% sales tax?
When the KRS 91A.400 tax is passed through to the customer, yes for purposes of the state calculation: 103 KAR 27:220 makes the passed-through amount part of Kentucky sales-taxable gross receipts.
Does 3% restaurant tax plus 6% state tax equal exactly 9%?
Not in the verified pass-through example. On $100, a 3% local charge creates a $103 state sales-tax base, producing $6.18 of Kentucky sales tax and a $109.18 total.
Who receives Kentucky local restaurant-tax payments?
Ultimately, KRS 91A.400 directs the revenue to the applicable tourist and convention commission. Merchants may file with the city, city finance department, clerk, or directly with the commission depending on the local ordinance.
Does the restaurant tax apply to takeout, delivery, and catering?
It can, but there is no safe one-line statewide answer for the local levy. Definitions and sourcing instructions must be checked city by city; several verified ordinances expressly reach off-premises food or catering.
How should I set up Kentucky restaurant taxes in my POS?
Use separate state and local tax codes, assign the correct bases, implement the tax-on-tax rule when the local levy is passed through, and map each code to separate liability and filing reports.
Kentucky Restaurant Tax: Verify the City Before You Configure the POS
A correct Kentucky restaurant tax setup starts with the jurisdiction, not with a default percentage in the POS. First confirm that the city is authorized under KRS 91A.400, then verify that it currently imposes the tax, the enacted rate, the taxable sales covered by the local ordinance, and the administrator that receives the return.
If the local restaurant tax is passed on to the customer, configure the POS so Kentucky’s 6% sales tax is calculated using the correct taxable base rather than simply combining the two nominal rates. Keep the state sales tax and local restaurant tax in separate reporting and liability accounts so each amount can be reconciled and remitted correctly.
Leave a Reply